Few concepts in personal finance are as misunderstood — or as powerful — as compound interest. It's the quiet engine behind wealth building, a mathematical force so effective that Albert Einstein allegedly called it "the eighth wonder of the world."
Whether you're saving for a home, investing for retirement, or simply trying to understand how money grows over time, compound interest is the single most important concept to master. In simple terms, compound interest means earning interest on your interest. But the real magic lies not just in the formula — it lies in time, patience, and consistency.
1. What Is Compound Interest?
Compound interest (sometimes called "interest on interest") is the result of reinvesting the interest you earn, rather than withdrawing it. When your interest is added back into your principal balance, the next interest calculation includes both the principal and the interest you previously earned.
This creates a snowball effect: every round of compounding makes your money grow faster than the round before.
Here's the difference:
- Simple interest: You only earn interest on the original amount you deposited.
- Compound interest: You earn interest on the original amount plus all the interest that has accumulated.
Most investment accounts, savings accounts, and long-term financial vehicles use compound interest to model reinvested earnings; investment outcomes are not predictable.
2. Why Time Is the Most Important Ingredient
When people talk about "letting your money work for you," they are really talking about giving compound interest enough time to do its job.
Imagine planting a seed: for a long time, not much seems to happen. But as seasons pass, that seed can grow into a tree. Compound interest works the same way — slowly at first, then astonishingly fast.
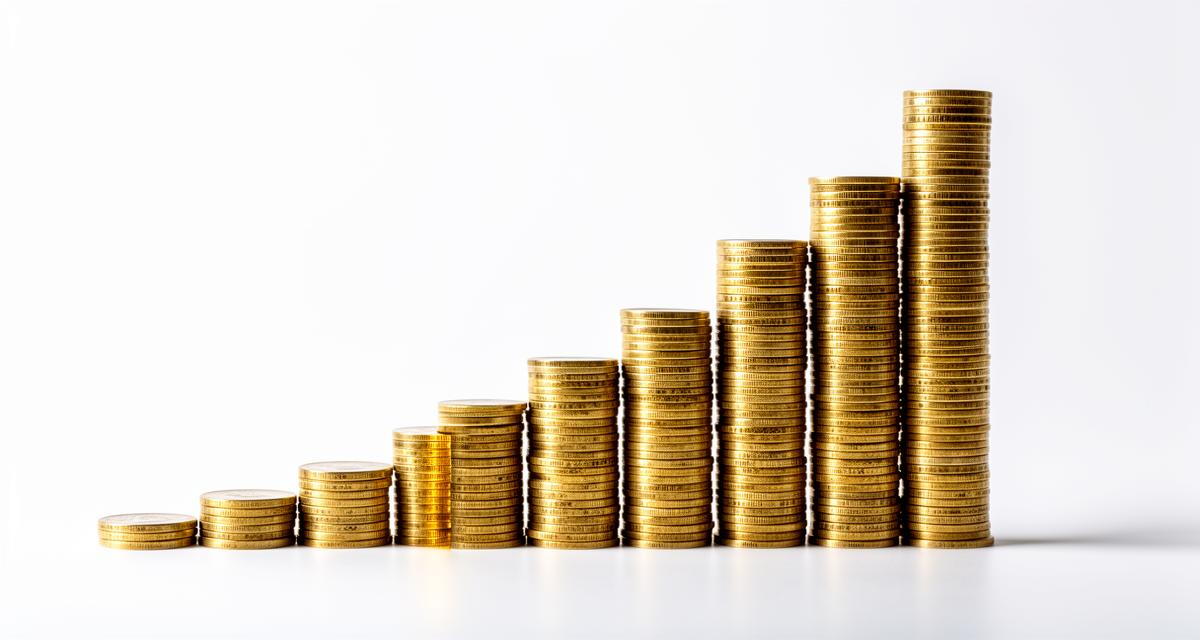
For example, $10,000 invested at 8% annual return:
- After 9 years (approx.), it doubles to $20,000
- After 18 years, it becomes $40,000
- After 27 years, $80,000
- After 36 years, $160,000
Notice something important: the last nine years produced far more growth than the first eighteen. That's the nature of exponential growth — time multiplies money.
This is why starting early is more important than starting big.
3. The Rule of 72: A Simple Shortcut
You don't need advanced math to understand how fast your money can grow. The Rule of 72 is an easy mental shortcut:
72 ÷ annual return (%) = approximate years to double your money
Examples:
- At 6% return: 72 ÷ 6 = 12 years
- At 8% return: 72 ÷ 8 = 9 years
- At 12% return: 72 ÷ 12 = 6 years
It isn't perfect, but it's surprisingly accurate — and it helps illustrate how even small increases in return can dramatically speed up wealth building.
4. How Compound Interest Works in the Real World
Savings Accounts
Even though interest rates on savings accounts are generally low, compound interest ensures your balance grows gradually over time. High-yield savings accounts make this more meaningful.
Stock Market Investments
Investment returns fluctuate. Reinvesting distributions can compound growth, but outcomes depend on the asset, period, fees and taxes; no unsourced nominal or real historical range is used here.
Retirement Accounts (401(k), IRA)
Tax advantages + compound interest = long-term wealth. Even modest contributions can grow into hundreds of thousands of dollars with enough time.
Debt (The Dark Side of Compounding)
Compound interest works against you when you carry high-interest debt like credit cards. Balances can grow out of control if left unpaid — a powerful reminder that compounding works both ways.
5. Why Compound Interest Is So Powerful
It Turns Small Amounts Into Large Sums
You don't need to save huge amounts to become wealthy. What matters most is consistency.
It Rewards Early Action
Time is your strongest ally. Starting ten years earlier often matters more than how much you invest.
It Does Not Eliminate Market Risk
A long holding period and reinvestment do not guarantee recovery from market losses.
It Requires No Effort
Once automated, compounding doesn't require daily involvement. The modeled balance assumes reinvestment and a constant rate; actual investments can decline.
6. The Math Behind Compound Interest (Explained Simply)
The basic formula for compound interest is:
A = P(1 + r/n)^(nt)
Where:
- A = final amount
- P = principal (your starting balance)
- r = interest rate (decimal)
- n = number of compounding periods per year
- t = time in years
Don't worry if formulas aren't your thing — the important part is this: More time, more compounding periods, and higher return = much bigger growth.
7. A Practical Example
Formula example, no additional deposits: $10,000 at a hypothetical 7% nominal annual rate gives about $19,672 after ten years with annual compounding. With monthly compounding at the same nominal rate, the existing model gives $20,097. The formula A = P(1 + r/n)^(nt) excludes subsequent deposits. APY already incorporates compounding, so comparing equal APYs would not produce this frequency advantage.
Use the Compound Interest Calculator to choose rate, frequency and deposits. For the separate starting-age decision, see starting at 25 versus 35. These are hypothetical nominal values before fees, taxes and inflation.
8. How to Use Compound Interest to Your Advantage
1. Start as early as possible
If you can't start big, start small. Time multiplies everything.
2. Automate your contributions
Automatic deposits ensure you never skip months.
3. Reinvest all earnings
Dividends, interest, and profits should stay invested.
4. Choose low-fee investments
Fees eat into compounding — even 1% per year can cost you hundreds of thousands over decades.
5. Stay invested
Compounding is a mathematical mechanism, not a guarantee that a market loss will reverse.
9. When Compound Interest Works Against You
Credit card debt is the prime example. With rates of 20–30%, compounding can double your balance shockingly fast.
Paying off high-interest debt is one of the best "investments" you can make — because it stops negative compounding.
Conclusion: Master This Concept, Master Your Financial Future
Compound interest is simple, but its impact is enormous. It explains how ordinary people can build wealth without winning the lottery, getting rich quick, or earning a massive salary. It rewards patience, discipline, and time — not luck.
If you understand compound interest and use it wisely, you'll be far ahead of most people financially.
It's the foundation of saving, investing, and long-term planning — the single most important concept in personal finance.